The Long View
Dave Ramsey’s Mortgage Rules Were Built for a Different Era
Dave Ramsey has one thing right; home prices aren’t coming down. Where he misses the mark (and the math) is advising qualified buyers to wait until they have 20% down. Here’s why.
Where Dave Ramsey Gets It Right
Dave Ramsey has helped millions of Americans get out of consumer debt. His core disciplines — stop spending more than you earn, eliminate high-interest debt, build an emergency fund — are sound principles, and for people in genuine financial distress, his framework provides structure that works. That part of his advice makes sense.
His mortgage strategy is a different matter.
Ramsey’s home buying prescription is specific: be completely debt-free first, save a 20% down payment, and take out no longer than a 15-year fixed-rate mortgage with a payment no greater than 25% of take-home pay. Follow those steps, he argues, and you’ll pay less interest, own your home outright faster, and avoid the financial ruin that debt can bring.
The rules sound disciplined. For a specific type of buyer in a specific type of market, they might be. But what about student loans? What about appreciation? What about how unaffordable a 15-year fixed is for even the most established homeowners today? His rules were developed in a different era, built on assumptions that no longer reflect the reality most first-time buyers face. Following them today, for most people, means missing years of wealth accumulation while waiting for conditions that may never arrive while spending increasing amounts on rent that never pays off.
Let’s look at the pros and cons of Ramsey’s home buying advice, so you can see if his rules make sense for you.
The Era These Rules Came From
Ramsey’s philosophy was forged from personal experience. In the late 1980s, he borrowed heavily against a real estate portfolio, the bank called his loans during a market downturn, and he went bankrupt at 26. He spent the following years rebuilding using strict debt-avoidance principles and published his first book, Financial Peace, in 1992.
The cultural backdrop matters. The post-WWII era that shaped mainstream American attitudes toward debt was defined by a cash economy, single-income households, stable long-term employment, and home prices that were two to three times annual wages coming off double-digit interest rates. Debt carried moral weight — it was associated with recklessness and failure. Mortgage-burning parties, in which homeowners literally set fire to their paid-off note in front of neighbors, were a genuine cultural ritual of the 1950s and 1960s. You got a job out of college and became a company person for the rest of your life, retiring with a gold pen and pension.
Ramsey’s rules made sense on the heels of that world when things went wrong for him nearly 40 years ago. The problem is neither of those worlds exist today. Home prices in most U.S. markets now run five to eight times median household income. Careers span multiple employers, jumping within 2-5 years on average, and often spanning multiple cities. The median first-time buyer is in their mid-thirties, not early-mid 20s. And wages have not kept pace with home prices for decades.
His framework calculates total interest paid over the life of a loan — a real number — but does not compare it to the total wealth generated by shorter period through leverage and appreciation and the demand of restructuring debt over time. He also comes from an era where it didn’t matter how good your credit was – the mortgage insurance required on loans with less than 20% down was expensive. Now, mortgage insurance has been significantly reduced.
All these omissions in the model are important to understand to how real estate is successfully bought and sold today.
This Is Not 2008
Before examining the numbers, one misconception is worth addressing right away, because it underlies much of the anxiety around low down payment mortgages. Dave bankrupted right on the heels of back-to-back financial crises when interest rates soared to 20% in the early 80s and followed the height of the S&L crisis. Leverage was not standardized or overseen properly, which helps make understandable his throwback to the values of ‘good, honest people’ who didn’t carry debt, or paid it off as fast as possible.
But we don’t have to look that far back to have concern about crisis. The 2008 meltdown remind us what else can go wrong. It’s important to contextualize what happened then so we can understand the risk today.
First and foremost, it’s important to underscore that responsible first-time homebuyers who income qualify were not the cause of the crisis. It was caused by no-documentation loans, negative amortization products, stated-income fraud at scale, and Wall Street packaging those loans into securities that were fraudulently rated as A paper. In other words, the failure was institutional and governmental, which let speculators get access to capital markets with little more than their word. The failure was not the underwriters approving the loans or the loan officers taking applications – it was the institutions and investors that wrote the guidelines they followed. Loans were approved for borrowers who had no proof of their ability to repay, and the loan packaging on the secondary market obscured that fact.
In 2010, the Ability to Repay Act was passed, which changed everything. Loans today follow strict underwriting guidelines, which includes proof of length of time at a job, the stability of the income, and good credit. Today, a loan that allows streamlined income qualification now requires large down payments, often 20-30% – amounts speculative investors think long and hard about before risking. To be clear, no one was foreclosed on back then randomly. It happened when borrowers couldn’t make their payments. But what hit the headline news, was the sensational cases of irresponsible borrowers who had overleveraged themselves, like Dave. This doesn’t mean debt is bad or irresponsible generally. Far from it.
Today, a buyer putting 3% down on a conventionally underwritten loan with verified income, documented assets, and a debt-to-income ratio within standard guidelines is not recreating 2008. The regulatory environment, underwriting standards, and loan products are categorically different. Conflating the two eras is one of the ways emotions — rather than facts — can drive people away from homeownership.
Why Waiting to Buy Can Cost You
Rent increases every year. A fixed mortgage payment doesn’t. The national average rent increase is around 5% annually (Monarch/Realtor.com, 2026), which means a renter paying $1,800 a month today is likely paying $2,300 by year five — for the same apartment. A fixed-rate mortgage taken out today has the same principal and interest payment in year five and ten years that it had in year one.
That difference compounds. Every year spent renting is a year of housing costs with nothing accumulating on the other side. No equity, no principal paydown, no appreciation. On a $400,000 home, five years of ownership typically builds $80,000 or more in equity through principal paydown and modest appreciation. Five years of renting builds zero for you.
The wealth gap this creates over time is significant, even if you have to move for work or life choices every 7 to 10 years. Over time, it adds up.
The Federal Reserve’s Survey of Consumer Finances puts the average homeowner’s net worth at 40 times that of the average renter. That number is the result of years of mortgage payments that build ownership stake while rents keep climbing.
I know you might be thinking, but Ramsey has you wait so you pay less interest in the future. Is that your reality? When can you afford nearly 2X the payment (15-year vs a 30-year fixed), be debt-free, and save 20% down? That isn’t the right way to think about it, because you are wasting rent and not accumulating wealth while waiting. It’s not free to wait. And getting started positions you to have the 20% down payment for your next house in 7-10 years through appreciation.
Timing the market is another concept that costs would-be buyers, because emotions shouldn’t rule the day — assessing the bottom line should.
When rates dropped sharply in 2020, home prices surged. Buyers who jumped in then rather than the year before when rates were two points higher found themselves with stiff competition to even win a house much less not pay over-asking. In short order, the most qualified buyers drove up the market, making a fortune for those who bought prior.
Things have cooled off, so that window has passed for now. But national appreciation over the past 70 plus years tells us that you can expect housing to appreciate at 3-4%, which on an asset that is hundreds of thousands of dollars, is the value of leverage. What would your same down payment have done for you in the bank? These are the questions to ask yourself.
The housing market remains strong: housing supply is still 3 to 4 million units short of demand nationally, and home prices are projected to rise 2 to 5% in 2026 regardless of what rates do (NAR; Zillow; Redfin, May 2026). Waiting is not a neutral position — the market moves while you’re watching it.
The final piece is payment reality. In most markets right now, a mortgage payment on a starter home is close to comparable rent. Some markets are significantly less, but only a few are nominally more. The average U.S. rent sits at approximately $1,850 per month as of mid-2025 (Zillow, 2025), while mortgage payments at current rates on modestly priced homes fall in a similar range depending on down payment and location. Regardless, there are tax benefits to help, and you are buying leverage which your rent doesn’t do.
None of this means buying is the right move for everyone right now. Not at all. Timeline, financial readiness, your career stability, and local market conditions all matter. But for buyers who can afford a 30-year fixed with low down payment and plan to stay put for five or more years, the cost of waiting is real, and it grows every year.
Home Financing Analysis (HFA)
A one-page comparison of your loan options — monthly impact, total cost, and break-even point. One page, three key numbers, one clear recommendation. No phone number required.
The Leverage and Time Value Ramsey Doesn’t Calculate
Two concepts we touched on that are largely absent from Ramsey’s framework are leverage and the time value of money.
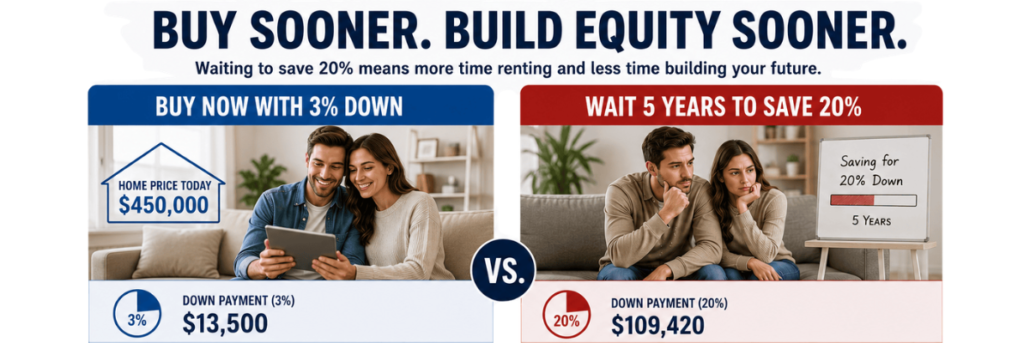
Leverage, in real estate, means using a mortgage to control an asset worth far more than your cash outlay. When you buy a $450,000 home with 3% down — $13,500 — you control a $450,000 appreciating asset. If that home appreciates 4% in year one, you’ve gained $18,000 on a $13,500 investment in one year. What would that $13,500 have paid you in a savings account? With real estate, you are leveraging a large asset with the same $13,500 – rather than multiplying by the face value.
In Ramsey’s framework, he’s treating the mortgage balance and total interest paid as the relevant number, which is a valid way to look at it, if you plan to follow the rest of the formula and see yourself achieving his prescription. A financial analysis, on the other hand, treats return on capital as the relevant number, and opens the door for more people to achieve the benefits. If you pay more in interest, how much does that matter if you 1) can’t ever meet the standard to enter the market, or 2) life doesn’t pan out as expected?
The time value of money, wasting rent, and appreciation combined with investing with a 30-year fixed now with as little as 3% down realistically far outweigh waiting on the sidelines for the perfect moment.
Time rewards those who take action, not waiting for the perfect weather. The cautionary tale is often the tale of loss.
Another important assumption of Ramsey’s principle is that when you buy, you will pay off the mortgage you start with (highly uncommon) and stay put for 15 years (also uncommon). There is a lot of the 1950s ethos in this reasoning, and if your life doesn’t support that rate situation, you’ll just lose.
The time value of money (TVM) is another point not considered in Ramsey’s method — that a dollar available today is worth more than a dollar available in five years. You see it in how $13,500 is worth less in 5 years. Every year passed saving toward a 20% down payment is a year the housing market moves like quicksand under your feet. Leverage what you have today and get on the right side of TVM.
The opportunity cost rule applied to today’s market – which in this case means that in paying more in interest, you win, as long as you do it consciously and with proper guidance.
The Math: Buying Now at 3% Down vs. Waiting 5 Years for 20% Down
Now that we’ve discussed the principles, let’s look at them in action with some real examples.
Purchase price: $450,000. Rate: Appreciation: 4% annually. Rent increase: 5% annually.
Scenario A — Buy now, 3% down, 30-year fixed at 6.5%
- Down payment: $13,500
- Loan amount: $436,500
- Monthly P&I: $2,759
- PMI: ~$309/month until approximately 20% equity (~year 10)
Scenario B — Wait 5 years, 20% down, 15-year fixed at 5.5%
- Home price in 2031 at 4% annual appreciation: $547,500
- Down payment: $109,500 (assumes you save it)
- Loan amount: $438,000
- Monthly P&I: $3,578
- Rent paid while waiting: ~$122,688
- Equity built while waiting: $0
| Buy Now | Wait 5 Years | |
|---|---|---|
| Purchase price | $450,000 | $547,500 |
| Cash to close | $13,500 | $109,500 |
| Monthly P&I | $2,759 | $3,578 |
| Monthly difference | — | $819 more |
| Rent paid waiting | $0 | ~$122,688 |
At the 10-Year Mark
Both buyers now own the same home, worth approximately $666,000 at 4% annual appreciation. Scenario A has owned for 10 years. Scenario B has owned for 5 years.
| Scenario A — Year 10 | Scenario B — Year 10 | |
|---|---|---|
| Home value | ~$666,000 | ~$666,000 |
| Principal paid down | ~$66,600 | ~$108,200 |
| Appreciation equity | ~$216,000 | ~$118,600 |
| Total equity | ~$282,600 | ~$226,900 |
| Rent paid | $0 | ~$122,688 |
| Extra cash deployed | — | ~$171,828 more |
| Net equity advantage | +$55,700 ahead | +$55,700 ahead |
Scenario B has paid down more principal — that is Ramsey’s point, and it’s valid. But Scenario A has more total equity, paid dramatically less to get there, and has been building wealth for twice as long.
This is also where most buyers sell. The median U.S. homeowner stays in their home for 12 years (Redfin, 2026). Less than 7% of Millennials have owned their current home for 10 years or longer. The 30-year payoff scenario most of Ramsey’s interest math depends on is not the scenario most buyers actually complete.
Total Interest Paid — Ramsey’s Argument
| Scenario A — 30yr | Scenario B — 15yr | |
|---|---|---|
| Loan amount | $436,500 | $438,000 |
| Total interest if held to term | ~$556,000 | ~$206,000 |
| Difference | ~$350,000 more on 30yr | ~$350,000 more on 30yr |
This is where Ramsey stops the analysis. The number is real. But it measures cost without measuring the asset.
Scenario A’s buyer, who purchased in 2026 and held to 2056, owns a home worth approximately $1,460,000 at 4% annual appreciation. The interest paid is the cost of controlling that asset for 30 years on a $13,500 initial investment. Scenario B’s buyer paid substantially less interest but deployed $109,500 upfront, paid $819 more per month for the life of the loan, and spent five years paying $122,688 in rent before the mortgage even started.
| Scenario A — Payoff 2056 | Scenario B — Payoff 2046 | |
|---|---|---|
| Year debt-free | 2056 | 2046 |
| Home value at payoff | ~$1,460,000 | ~$985,000 |
| Total interest paid | ~$556,000 | ~$206,000 |
| Rent paid waiting | $0 | ~$122,688 |
| Down payment | $13,500 | $109,500 |
| Total cash out of pocket | ~$569,500 | ~$438,200 |
| Net equity at payoff | ~$1,460,000 | ~$985,000 |
Scenario B pays less out of pocket and is debt-free 10 years sooner. Those are genuine advantages. But Scenario A finishes with $475,000 more in equity — the direct result of controlling an appreciating asset for a decade longer, which washes out the bottom-line Dave is ‘saving’ you.
And all of this has a lot of assumptions in it you might not be up for.
The Flexibility the 30-Year Provides
Ramsey’s 15-year rule optimizes for one outcome: paying the least interest on a fixed timeline. What it removes is flexibility — and flexibility has real financial value, particularly in the early years of a career when income is less predictable, families are growing, and life doesn’t follow a script.
A 30-year mortgage at $2,759 per month can be accelerated at any time to cut years of the mortgage to achieve similar results. Adding $500 per month to principal at 6.5% cuts the payoff by approximately 8 years and saves roughly $180,000 in interest. The option to pay more is always available. The option to pay less on a 15-year mortgage when a job changes, a medical bill arrives, or a family situation shifts is not. And waiting to start, as we’ve covered, isn’t a benefit to you.
Ramsey’s model does not account for the unexpected, including debt consolidation, which is one of the most common and financially sound uses of home equity — rolling high-interest consumer debt into a lower-rate mortgage obligation to pay for medical or children’s school expenses. Nor does it account for career relocation, family size changes, or any of the variables that cause real people to sell homes before a mortgage runs its course. His framework assumes a stable, linear life. Most lives are not.
The Hidden Assumption: That You’ll Stay and Pay It Off
Only 28% of working-age homeowners under 65 have paid off their homes, according to Census Bureau data. Among homeowners 65 and over, the figure is 63%. Paying off a mortgage is largely a retirement-age outcome — not a working-life one, regardless of intention.
The median U.S. homeowner stays in their home for 12 years (Redfin, 2026). At that point the home sells, the mortgage pays off from proceeds, and the equity rolls into the next purchase. The relevant question is not “how do I minimize interest over 30 years?” It is “how much equity do I build between now and when I sell, and what did it cost me to get there?”
On that timeline — the timeline most buyers actually live — entering the market earlier with a lower down payment and a manageable payment consistently outperforms waiting. Not because debt is good, but because time in the market is. And because a fixed payment on an appreciating asset is one of the most reliable wealth-building mechanisms available to working Americans.
Who Ramsey’s Rules Is For
Ramsey’s mortgage framework works well for a specific profile: someone with significant consumer debt who has demonstrated difficulty living within their means, managing credit, needs behavioral guardrails to avoid over-leveraging, and has the income to support a 15-year payment comfortably after achieving complete debt freedom. For that person, his rules provide discipline that produces real results.
They are not designed for — and do not serve — a financially stable first-time buyer with manageable debt, steady income, a solid credit profile, and a five-plus year horizon who simply hasn’t had 5-10 years to save a 20% down payment.
For the second buyer, which describes most first-time buyers in today’s market, the math points in a different direction. Enter the market. Lock in the payment. Let appreciation and time do the work. Accelerate when you can. Sell when life requires it. Roll the equity forward.
That is an equally valid and more accessible way to build wealth through homeownership. Not by waiting for perfect conditions that the market keeps moving out of reach. By starting.
Ready to get started with a pre-approval or refinance?
Request a Home Financing Analysis (HFA)
A one-page comparison of your loan options, focused on monthly impact, total cost, and break-even point. Three key numbers. One clear recommendation. No phone number required.
The Buyer’s Briefing
What the Mortgage Industry Doesn’t Tell First-Time Buyers
From someone who’s been in it 20 years.
Most buyers know the APR is more important than the rate alone. They know points paid upfront affect the effective cost of the loan. They’ve read that the Fed doesn’t directly set mortgage rates, and that bond markets are the more relevant force for forecasting.
That’s a solid foundation. What’s harder to find — because the industry doesn’t explain it and has no particular incentive to — is how loans are priced, why the moment you lock can matter as much to your pricing as trying to nail down the price on a single day, why a buydown may not be priced competitively relative to the market, and why the lender you choose is ultimately a bet on execution, not just a number.
None of this is inaccessible or hard to understand. It’s just not explained. That’s what this article will cover.
The rate you’re quoted is not “the market rate”
When mortgage rates make the news, they’re reported as a single number — “rates are at 6.5% this week.” That implies there’s a set rate, available to everyone, which isn’t accurate.
Mortgage pricing starts with wholesale market rates, which move continuously based on bond market activity, inflation expectations, and investor demand for mortgage-backed securities. Those wholesale rates are not what borrowers see. What borrowers see is that rate plus a margin — the lender’s cost of doing business and whether they hedge — layered on top of the underlying rate.
That margin is not the same across lenders. It reflects the lender’s overhead, staffing model, profit targets, and current loan volume. A lender running a national call center with heavy advertising costs prices those costs into every loan. A lender with lower overhead prices differently. It’s also based on the average loan size for the area. The margin’s value to the lender is in the multiplication of the margin times the loan amount.
Thus, two borrowers with identical credit profiles, identical loan amounts, and identical property types can receive meaningfully different quotes on the same day from different lenders — not because the market treated them disparately, but because the lender quoting them serves different markets with different core business models.
This also means that a lender priced competitively today may not be tomorrow — deliberately. If a lender gets too busy, exceeds processing capacity, or hits a volume target, they raise their margin to slow incoming business. Another lender, trying to generate volume or build a reputation, drops their margin to pull in more loans. The competitive position shifts constantly and has nothing to do with the borrower’s file.
A mortgage broker with access to hundreds of wholesale lenders is comparing those margins across the market in real time. But it’s important to note that not all brokers track the wider wholesale market, which has hit the news in recent years. Some act more as agents for a single lender, most notably UWM. That doesn’t mean UWM might not have the best loan option for a borrower on a given day. It just means UWM has been known to be out of market for months at a time, so they aren’t always the best. Through broker incentives, they encourage brokers to submit to them nearly exclusively while referring to them as independent. You’ll want to do your own research if this matters to you.
Home Financing Analysis (HFA)
A one-page comparison of your loan options — monthly impact, total cost, and break-even point. One page, three key numbers, one clear recommendation. No phone number required.
Locking a rate is a decision, not a formality
Many lenders treat the rate lock as a step in the paperwork — something that happens when the lender says it’s time. That’s not strategic. The rate lock should be a market timing decision, because it has real financial consequences.
Locking early secures your rate and pricing against the market moving against you before closing. That certainty has value, particularly when closing is short or when market conditions are volatile or in an upward pressure cycle.
Waiting to lock, called floating the rate, can make sense when there is enough time before closing, pricing appears to be near the high end of its recent range, and there isn’t concern of jeopardizing the transaction should rates unexpectedly go the other direction. It is not a strategy for outguessing the market — nobody consistently does that. It is a judgment about where pricing sits in its current cycle, because there is a reliable 2–3-week cycle and knowledge about upcoming financial news.
Two forces are always in play simultaneously, which is why locking should be a conversation. The first is the short-term cycle — the predictable oscillation within a range that an experienced broker can read and use to inform timing. The second is external events — geopolitical developments, unexpected economic data, Federal Reserve signals — that can move pricing sharply in either direction without warning. The first is manageable. The second is not predictable. A sound lock strategy accounts for both.
What this means practically: the conversation about when to lock should happen before you lock. You can request your loan officer to watch the market for a good day to lock, and a good one will be able to.
Whether to buy down your rate — and when the cost is worth it
Most lenders will offer you the option to pay points upfront — a percentage of the loan amount paid at closing — in exchange for a lower interest rate. This is called buying down the rate, and it can make financial sense in some cases. It can also be one of the most consistently misrepresented calculations in the mortgage process.
The math is straightforward in principle. You pay a known amount today to reduce your monthly payment by a known amount going forward. Divide the upfront cost by the monthly savings and you get your breakeven — the number of months it takes to recover what you paid. If you keep the loan longer than that, the buydown saves you money. If you sell, refinance, or pay off the loan before that point, you pay for a discount you never received.
Where it gets complicated is the pricing of the buydown. A buydown is only as good as the rate reduction it actually produces relative to its cost. Lenders have different strategies with their buydowns — either pricing it well, with the idea that you’ll have less incentive to refinance so they hold the loan longer, or pricing it poorly so they make a lot on the few people who do buy it down while maintaining an aggressive strategy of refinancing you at the first opportunity.
The questions worth asking before buying down a rate: How long do you realistically expect to keep this loan? What else could that upfront cash do? And is the buydown pricing you’re being offered actually competitive compared to other lenders?
A broker who has compared buydown pricing across multiple wholesale lenders can answer that last question. But a good rule of thumb is: a bad buydown is paying 2 points for .25 in rate. A good buydown is closer to 2 points for a half-point in rate.
But this also depends on your loan size, breakeven, and your long-term plans with your home. If you have a question about this — as a broker, we review loan offers from lenders all day, every day. We’d be happy to review an offer for a second expert opinion.
What you’re actually evaluating when you choose a lender
Rate, lock timing, and buydown are all things a knowledgeable broker can help you navigate. But there is a fourth variable that borrowers rarely evaluate and almost always wish they had: what happens when something goes wrong.
Mortgages do not always close cleanly. Appraisals come in below contract price. Underwriters issue conditions that require documentation that takes time to gather. Title searches produce surprises. Closing dates slip. In a purchase transaction, where a seller is waiting, where a moving date is set, and where earnest money is at risk, the difference between a lender who can solve problems quickly and one who cannot gets real.
A national call center processes volume. It is staffed to handle the straightforward file efficiently. When a file becomes complicated — and first-time buyer files often do, because first-time buyers have less straightforward income histories, thinner credit profiles, and less experience knowing what documentation is needed — the call center model has limited capacity to respond. You get a different person each time you call. Nobody owns your file. Escalation is slow and confusing.
This is the cost that doesn’t appear in the rate quote. It shows up at 4pm on a Thursday before a Friday closing, when you need someone to pick up the phone and solve something.
The way to evaluate a lender on this dimension is not to ask them how good their service is. Every lender says their service is excellent. The way to evaluate it is to ask specific questions: Who handles my file from application to close, and how do I reach them directly? What happens if my closing date needs to move? Can you explain what conditions typically come up on a file like mine and how they get resolved?
The answers — and the confidence or hesitation behind them — tell you more than the rate quote.
What to compare when you’re evaluating your lender options
The rate matters. It has real monthly consequences and compounds over time. But how your loan is structured can end up being just as important to what you pay.
One aspect is the lock timing. A rate quote is good for the day.
Another is whether to pay points or receive a credit, and if so, how much.
Ultimately, this is based on you and your circumstances. If a lender isn’t asking you about your plans with the property, they aren’t assessing your options for you thoroughly.
Lastly, the person or team behind the transaction matters in ways that only become visible when the transaction gets complicated. By then, the rate comparison is long behind you.
The borrowers who come out best aren’t the DIYers, but the ones who effectively interview the lending agent and vet their reputation. They are the ones who find someone with real market access, ask the right questions early, and stay in the conversation through to close.
All of it — how the rate is built, when to lock it, whether a buydown pencils out, what happens when the file gets complicated — comes down to the same thing. Whether the person on the other side of the transaction has the sourcing to find you the best available pricing, the knowledge to structure the loan correctly for your situation, and the incentive to do both of those things in your interest rather than the bank’s. That last part is the one the industry makes hardest to evaluate. It doesn’t show up on a Loan Estimate. It shows up in how someone answers a hard question, what they tell you when the honest answer isn’t the convenient one, and whether they’re still reachable when something needs to be solved.
Ready to get started with a pre-approval or refinance?
Request a Home Financing Analysis (HFA)
A one-page comparison of your loan options, focused on monthly impact, total cost, and break-even point. Three key numbers. One clear recommendation. Learn more.
Spring 2026 Housing Trends
If you’re trying to figure out how world events affect your home, your equity, or your next move, that’s what we’re breaking down……. [READ MORE]